When the CRA Questions Your Business Expenses: A Practical Guide for Canadian Small Business Owners

You begin by noting that receiving a letter requesting documentation regarding a business expense previously claimed on a tax return can be unsettling for small business owners. While the letter may indicate nothing is wrong, it is likely a trigger for anxiety. At least, it certainly was for me. Many of us have claimed certain expenses without properly documenting them. Therefore, it is essential to prepare yourself ahead of time to avoid unnecessary stress. The key areas to focus on are the following:
- Understanding what the CRA is looking for
- Tracing a Claim back to its records
- Preparing a complete, organized and well-documented package of supporting materials
The first step is to read the CRA correspondence carefully to determine what is expected. This will help you save time and energy in preparing your response. Specifically, you want to find out:
- Which tax years the CRA is reviewing?
- What expense categories are included in the review?
- What specific documents does the CRA require?
Record the response due date and submission method. Once you know what you have to provide and when, you can start organizing the necessary paperwork.
You mention that there is a difference between a request to support a particular expense and a full-blown audit of multiple years and accounts. Although both require a response from you, the volume of documentation required and the time needed to assemble it differs greatly. For example, you might be required to produce detailed records for only a few months, whereas an audit could cover five years or more.
If you receive an unexpected request, or if you get an email or text message requesting personal or financial information, take a moment to verify it through legitimate CRA channels. According to the CRA website, they publish information about how they contact taxpayers, and verifying through My Business Account or checking a phone number listed on the CRA website is an acceptable way to verify before sharing sensitive information.
You also mention that you don’t have to include all of your records in your response. A focused, accurate response that answers what was actually asked is more helpful than providing a comprehensive response that overwhelms the reviewer with irrelevant data.
Your best bet is to move in One direction: from the number on the return back to the receipts. First, locate the amount reported on the return for the year in question. If the expense was reported as a total amount, then that total is your starting point.
Next, list each transaction that adds up to that amount. These can come from your accounting program, a spreadsheet or a manual ledger.
Finally match each transaction to its corresponding supporting document. In addition, explain how any mixed business and personal use was accounted for.
Creating a table of all the transactions and their associated supporting documents works very well. Columns for date, supplier name, amount, business purpose, percent of use (if applicable), and document reference allow a reviewer to easily follow your logic and immediately see any missing pieces. Where a transaction does not have an accompanying document, your table will clearly display it rather than hiding it until someone requests clarification.
Also be aware that different types of supporting documents serve different purposes. For example: an invoice indicates what was delivered and at what price; a payment receipt confirms that funds were exchanged; a dated note indicating why an expense occurred demonstrates business intent; none of these prove deductibility individually and the stronger position typically comes from having more than One of them indicating the same conclusion.
An important note: the rules for businesses owned by sole proprietors differ slightly from those for corporations. The remainder of this section will focus on sole proprietorship expenses, as they relate to the CRA’s normal procedures.
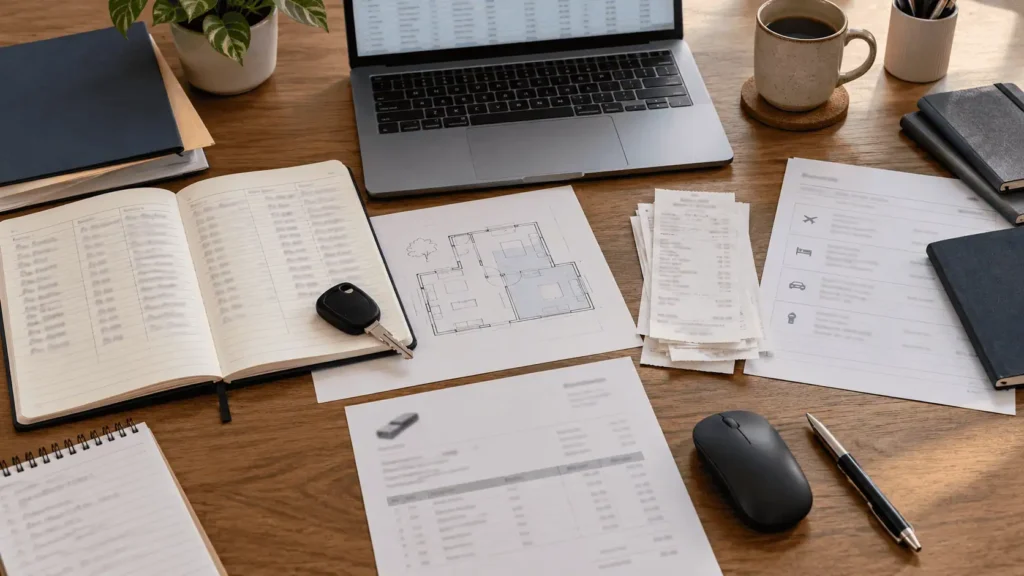
Here are Five expense types of worth doublechecking thoroughly:
1. Vehicle expenses
Claims for vehicle usage depend primarily on the question of what percentage of vehicle use was for business. Since you need to demonstrate that ratio, keep separate records of both business-related use and nonbusiness related use of the vehicle. Simply tracking overall kilometers traveled will not suffice.
While maintaining a daily log of miles driven during business hours is more beneficial than trying to create One retrospectively at yearend, knowing how far you drove for business relative to overall mileage makes an allocation possible. Additionally, fuel, insurance, maintenance and license fees should be apportioned based upon the same percentage as mileage use.
For those interested in knowing precisely what forms a log book must contain according to CRA regulations, please consult current CRA guidelines as this has evolved over time.
2. Home use for business
Both eligibility for home use deductions and calculating them can be just as important as retaining receipts. Supporting amounts for utilities like heat, electricity, insurance or rent validate what you are claiming. However demonstrating both eligibility (that part of your home meets CRA criteria) and how you determined the business use ratio is also important.
Documentation of your workspace is equally important. A diagram of your floor plan showing area(s) used as workspace (and measurements) plus notes detailing actual uses will help support both eligibility and ratios. Where part of your space is used for both business and personal purposes, your rationale for allocating business shares should be understandable.
Please be cautious not to confuse two completely distinct sets of rules. Home use for self-employment deductions differs substantially from employee home office allowances and differing tests and computations are employed. Misapplication of either framework frequently results in an assessment.
3. Meals and entertainment
Collecting itemized receipts is better than saving only the summary slip since summaries rarely capture details about what was ordered or by whom. Recording who was present and the purpose of meals/entertainment is significantly more helpful than an unsupported receipt.
Additional limitations and exceptions apply to meals and entertainment claims as per current CRA publications so please refer to current publications prior to employing a specific strategy.
While an itemized receipt demonstrates that money was expended on food, it does not demonstrate a valid business purpose nor does it establish that there was any business purpose. Establishing business purpose is critical since CRA limits meals/dining expenditures exclusively to those involving clients or business associates.
4. Travel expenses
Establishing purpose is central to travel expenses. Documentation establishing where you went, when you traveled and what your intention (purpose) for traveling was will form strong support for a travel expense claim. Emails confirming travel plans or appointments, meeting notifications/registrations etc., all provide significant documentary support.
Care must be exercised when documenting mixed trips. When travel incorporates both business and personal activities, the deduction typically relates only to the business use segment rather than the entire cost of travel and accordingly a basis must be established for determining what portion constitutes “use” – i.e. What was done in support of the business vs. Personally. Documentation establishing purpose will similarly assist in establishing validity of an allocation methodology.
5. Equipment repair/purchase
Distinguishing between operating expenses and capital expenditures revolves around characterizing the nature of acquisitions rather than dollar values.
Typically repairs that are done to get things back to their operational status will be separate from enhancements/improvements that add long term value. Equipment that is purchased and used within your business would generally be considered a capital asset. The expense for the purchase of this type of equipment can be depreciated over time using a capital cost allowance (CCA) class, rather than being written off as a current expense.
Example hypothetical: a consultant travels to attend client meetings in addition to enjoying two extra days off while traveling. He pays for airfare, accommodations and food using his corporate credit card and he reports the $5,000 total as travel expenses. In order to support his claim he would need to demonstrate that three client meetings did occur during that trip and that the trip’s predominant purpose was business; he would also need to justify how he allocated time/personal activities among his three days away from home.
Documents rarely speak directly to the question posed by regulatory bodies’ rules themselves although they may offer supporting evidence indirectly.
When some or all documents are unavailable
Losing documentation is common. How you react is more important than the loss itself.
Contact suppliers to obtain duplicate invoices when possible since many will resubmit originals upon request especially if account activity remains ongoing. Retrieve archived bank & credit card statements which may prove payment regardless of availability of itemized receipts. Check hotel reservation records; contracts; emails with attachments referencing accounting journal entries etc.; as these may hold more detail than your accounting software retains.
If truly unable to locate something, write down what you cannot access & describe what you can retrieve this provides reviewers with clarity. Evidence generated retroactively is evaluated on merit; therefore presenting estimates as estimates can help mitigate rejection risk.
Do not create new documentation or modify existing documentation nor attempt to characterize personal spending as business expenditures this converts a documentation deficiency into a potentially severe offense.
Finally distinguish between deficiencies in documentation expense incurred for business purposes and errors expense not related to business or excessive amounts claimed as these call for different responses; identifying which case exists is step 1.
Organize your submission clearly
Submit your package of supporting documentation consistent with what was requested in sequence & in the manner originally specified.
Label documents uniformly e.g.: year / type so contents can be identified without opening them.
Provide concise explanations for each questionable Claim identify supporting documents.
Outlining any calculation provides a basis for any percentage allocations.
Maintain duplicates of all submitted materials along with CRA communications surrounding your audit in case this becomes a continuing concern.
Where deadlines are unrealistically tight, contact CRA early on to discuss requests before submitting incomplete packages.
Extensions are not automatically provided therefore contact CRA prior to the deadline rather than afterward.
Review your options after proposed changes
Proposed adjustments constitute something distinctly separate from objections raised toward formal assessments although both result in changes being considered toward your taxes owed.
A Proposal Letter is an opportunity for taxpayers to have the chance to provide additional information/evidence about any Proposals before they become Finalized. The Proposal Letter provides taxpayer’s with an opportunity to add more information/evidence before the Assessment becomes finalized. Once an Assessment has been issued that represents a Formal Proceeding. In addition to the difference in Action Possibilities after an Assessment has been Issued versus during Initial Proceedings.
Once Assessments are issued, identify specifically what Facts or Interpretations challenge CRA’s Position(s) relative to the Assessment. If Additional Evidence resolves the Conflict, then there would be no need for further action. However, if the Differences are related to how Provisions Apply, etc., then Taxpayers should consider their Rights to Verify Applicable Timeframes referenced in Notice as opposed to assuming when they begin as it begins on Issue Date of Assessment.
Where several years of records or disputed expense allocations are involved, taxpayers may seek professional assistance to organise the evidence and understand the process.
CRA audit services are one option for that support, and it is worth asking any adviser what the engagement covers, what records are needed, and who remains responsible for the accuracy of what is filed.
Frequently Asked Questions
Does a CRA request for receipts indicate that I am going to be audited?
No. CRA’s decision to request receipts will depend upon the subject matter of the correspondence. For example, a request to provide receipts in support of a single claim is less likely to represent a full audit of multiple accounts over several years. Before taking action regarding the correspondence, read the letter carefully to determine exactly what you are asked to do.
Is there sufficient documentation to justify an expense using a bank or credit card statement?
Bank and credit card statements confirm a payment, verify the amount paid and document the payment date. Generally, these documents will not identify either what the payment represents or how this relates to your business. If the business relationship is not clearly documented by the payment record alone (i.e., where an invoice or other supporting information cannot be identified), further documentation such as an invoice or supporting rationale for making the purchase may need to be provided in order to support deductibility.
If an expense was used for both business and personal purposes; how do I apply CRA’s rules?
To apply CRA’s rules regarding mixed-use expenses, you must consider all of the available evidence in order to accurately allocate the expense between the business and non-business portions. Supporting records of how the business portion was determined must also accompany the allocation. While allocating at the time of application is simpler than attempting to estimate later, documenting the method of allocation at the time you make the calculation provides better evidence and credibility for your position.
Do I have grounds to dispute a CRA re-assessment of my expenses that denies my claims?
Yes. Objections based upon a CRA re-assessment denial of an expense claim are available and expire after receipt of the CRA notice of assessment. Check the notice of assessment for the applicable appeal deadline. In general, objections based upon the CRA re-assessment will rely upon substantially the same documentation that supported your original claim. Additionally, you should provide an explanation of why you believe the assessment denying your claim is unreasonable.
Also read: